Home Insurance in Keller, TX: Local Coverage Guide for 2026 in Texas
Home insurance in Keller, TX: what every homeowner should know
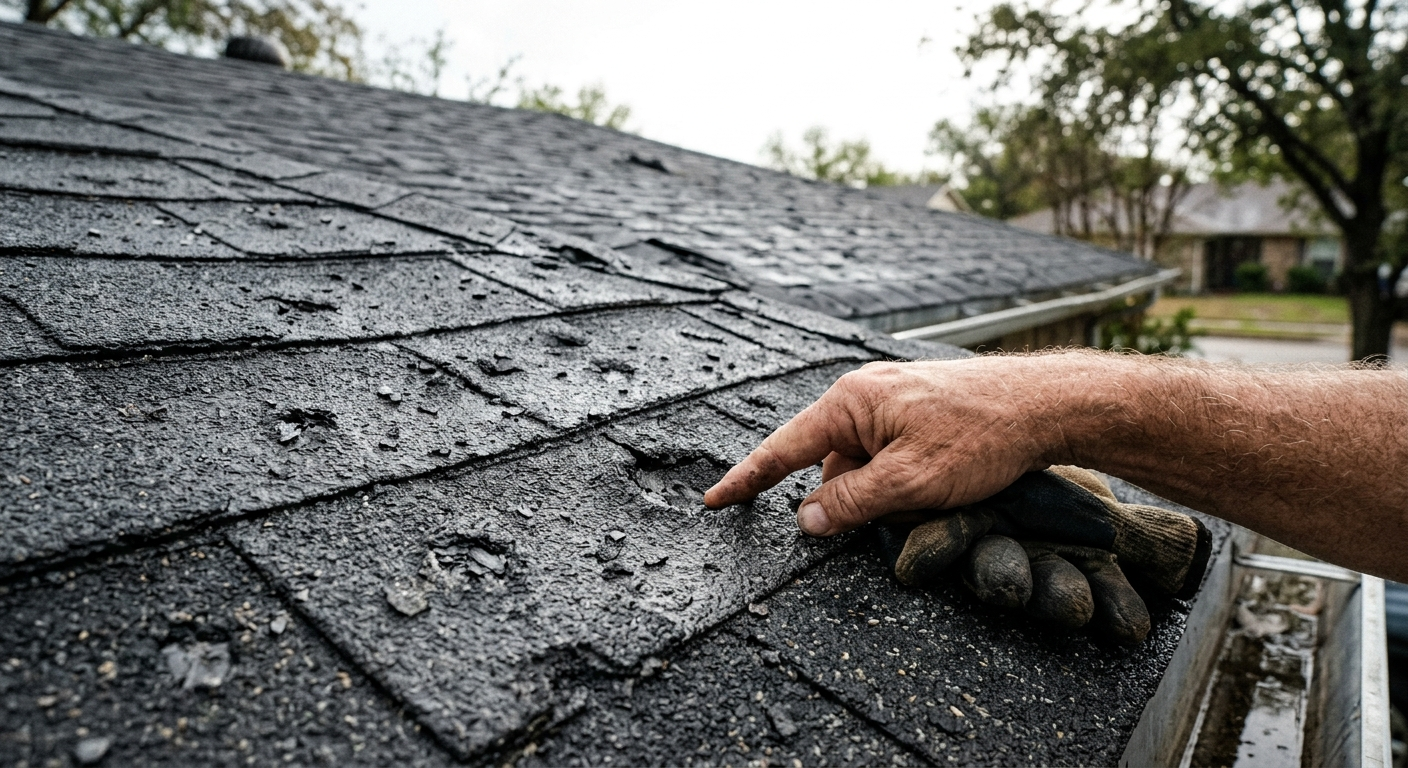
If you own a home in Keller, you already know this is one of the most desirable places to live in the DFW Metroplex. Excellent schools, newer construction, strong property values, and a close community make it an easy choice. But home insurance in Keller, TX comes with its own set of considerations that are easy to overlook until something goes wrong. Hail the size of golf balls, severe thunderstorms, and the occasional tornado watch are part of life in Tarrant County, and the right policy is what stands between a bad weather event and a serious financial loss.
Why Keller homeowners face unique coverage challenges
Keller sits in North Texas, a region that routinely ranks among the most hail-prone areas in the country. The National Weather Service has recorded multiple significant hail events across Tarrant and neighboring counties each year, and roofing contractors in the 76248 and 76262 zip codes stay busy because of it. That risk directly affects how carriers price policies and what they will and will not pay after a claim.
Beyond hail, there are a few other local realities worth knowing:
- Expansive clay soil. Keller's soil shifts dramatically with moisture changes, which can cause foundation movement. Standard home insurance does not cover gradual foundation settling, so understanding what your policy excludes matters.
- Flash flooding. Several creek systems run through Keller and the broader northwest Tarrant County area. Even properties not in a mapped flood zone can flood during heavy rain events, and standard homeowners policies exclude flood damage entirely.
- Newer construction costs. Many Keller homes were built in the 2000s and 2010s with features that are expensive to replace, including modern roofing systems, open floor plans, and upgraded finishes. Insuring to actual replacement cost rather than market value matters more than most people realize.
If you have filed a hail claim or are curious how the process works in Texas, our post on hail damage home insurance claims in Texas walks through what to expect step by step.
What a standard Keller homeowners policy actually covers
A standard HO-3 policy, which is the most common form for owner-occupied homes in Texas, covers your dwelling, other structures, personal property, loss of use, liability, and medical payments to others. Here is what each piece means in practice:
- Dwelling coverage (Coverage A). Pays to repair or rebuild your home's structure after a covered loss. This should be set to your home's replacement cost , not its market or appraised value. In Keller, construction costs have risen sharply, so many homeowners are underinsured without realizing it.
- Other structures (Coverage B). Covers detached garages, fences, storage buildings, and similar structures. Typically 10% of Coverage A by default, but that can be adjusted.
- Personal property (Coverage C). Covers your belongings, furniture, electronics, clothing, and more after a covered peril. Many policies pay actual cash value (depreciated) by default. Replacement cost coverage on personal property is worth the small premium increase.
- Loss of use (Coverage D). Pays for temporary housing and living expenses if your home is uninhabitable after a covered loss. This matters most when a storm causes serious damage.
- Personal liability (Coverage E). Covers you if someone is injured on your property and sues. Standard limits often start at $100,000, but $300,000 or more is a better fit for most Keller households, especially those with pools or trampolines.
- Medical payments (Coverage F). A small limit (typically $1,000-$5,000) for medical bills of guests injured on your property, regardless of fault.
You can learn more about the full range of homeowners insurance options available through Firstline Insurance Agency.
Coverage gaps that catch Keller homeowners off guard
Even a well-written policy has limits, and North Texas hazards have a way of exposing them. The most common ones we see in Keller:
Wind and hail deductibles
Texas insurers are allowed to apply a separate, higher deductible specifically for wind and hail claims. This is not the same as your standard deductible. It is usually expressed as a percentage of Coverage A (commonly 1% or 2%, sometimes higher in high-risk areas). On a home insured for $450,000 , a 2% wind/hail deductible means you pay the first $9,000 out of pocket before the carrier covers anything. Read your declarations page carefully and make sure you understand what you are agreeing to.
Flood exclusion
Every standard homeowners policy excludes flood, full stop. Keller has areas near Bear Creek and other drainages where this matters. Personal flood insurance is available separately, either through the National Flood Insurance Program (NFIP) or through private carriers that often offer broader coverage and faster claims settlement. Our post on personal flood insurance for Texas homeowners explains your options in detail.
Sewer and water backup
Damage from a backed-up sewer or drain is not covered under a standard policy. A water backup endorsement is usually available for $50-$100 per year and is worth adding.
Jewelry and valuables
Personal property coverage has sub-limits for jewelry (commonly $1,500), guns, and silverware. If you have engagement rings, watches, or other high-value items, a scheduled personal property endorsement or a standalone jewelry policy is the right move.
Liability limits
Pools, trampolines, and dogs all create liability exposure. If your standard liability limit feels thin, a personal umbrella policy layers additional protection on top. Our page on personal umbrella insurance in Texas explains how this works and why it costs less than most people expect.
How much does home insurance cost in Keller, TX?
Texas home insurance rates are among the highest in the country, driven by hail, wind, and litigation frequency. In Keller, homeowners are generally looking at somewhere between $2,000 and $4,500 per year depending on home size, age, construction type, claims history, and the coverage options selected. The variables that drive your specific number include:
- Roof age and material. A roof over 10-15 years old will cost more to insure. Impact-resistant (Class 4) roofing materials can earn a meaningful discount with some carriers, sometimes 20-30% off the wind/hail portion of premium.
- Coverage A amount. The replacement cost you select is the single biggest driver of premium. Make sure you are not over-insuring or, more commonly, under-insuring.
- Deductible choices. A higher wind/hail deductible lowers your premium but shifts more risk onto you after a storm.
- Claims history. Both your personal claims history and the property's prior claims history affect pricing. Texas uses the CLUE (Comprehensive Loss Underwriting Exchange) report, which carriers pull during underwriting.
- Credit score. Texas allows insurers to use credit-based insurance scores. Improving your credit can lower your premium over time.
- Carrier competition. Rates for the same home can vary by 30-50% across carriers. An independent agent shops multiple carriers at once, which is the core advantage Firstline offers compared to a captive agent locked into one company's rates.
For broader context on what drives home insurance pricing across the Fort Worth area, see our breakdown of Fort Worth home insurance cost factors.
Keller-specific tips to lower your premium without cutting real coverage
Saving money on home insurance does not have to mean accepting worse protection. These steps work in the Keller market:
- Upgrade your roof proactively. If your roof is approaching 15 years, the premium savings from a Class 4 impact-resistant replacement can sometimes pay back the cost in just a few years. Ask your agent to model out the numbers before you replace.
- Bundle with auto. Multi-policy discounts (home plus auto) typically range from 5-15% depending on the carrier. Bundling also simplifies your coverage into one relationship.
- Install monitored security and smoke detection. Most carriers give discounts for centrally monitored burglar and fire alarm systems.
- Review Coverage A annually. Construction costs have risen fast. Make sure your dwelling limit reflects current rebuild costs, not what it was three years ago. Being underinsured at claim time is far more expensive than a small premium increase today.
- Shop at renewal. Texas home insurance is a competitive market. If you have not compared carriers in the last two to three years, you may be overpaying. An independent agency like Firstline can run the comparison for you.
Do you need flood insurance in Keller?
More homeowners than you might expect do. FEMA flood maps define "high-risk" flood zones, but a large share of flood claims happen outside those zones. In Tarrant County, heavy rain events (including the kind of multi-inch rainfall Keller can see from a single line of thunderstorms) push water into areas that look safe on paper.
If your lender does not require flood insurance, that does not mean your home cannot flood. It just means no one is requiring you to buy protection. Private flood insurance options have improved significantly in recent years, offering broader coverage, faster claims, and sometimes lower prices than NFIP policies. It is worth a conversation before the next severe rain season arrives.
Working with a local independent agent in Keller
There is a real difference between shopping for home insurance online and working with an agent who knows the Keller market. Local independent agents know which carriers are actively writing new business in 76248, which ones are tightening underwriting on older roofs, and which ones handle hail claims well versus which ones contest every claim. That local knowledge leads to better placement and fewer surprises.
Firstline Insurance Agency is a local, independent agency serving Keller and the surrounding communities including the Keller service area. As an independent agency, Firstline is not locked into one carrier's rates or products. The team shops across multiple admitted and surplus lines carriers to find the combination of coverage and price that fits your specific home and situation.
If you are wondering how to find the right local coverage partner more broadly, our post on finding the right insurance agency in Keller 76248 is a good starting point.
Get a home insurance quote for your Keller home
Whether you are buying your first home in Keller, coming up on renewal, or just want to know if you are getting a fair deal, Firstline Insurance Agency is ready to help. The team compares multiple carriers on your behalf, walks you through coverage options in plain language, and makes sure you are not leaving gaps that could cost you later.
Call (817) 618-5480 or reach out online through the contact page to get started. No pressure, no jargon, just straightforward advice from a local agency that knows what Keller homeowners are up against.
Get A Quote
At Firstline Insurance Agency, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Firstline Insurance Agency
Recent Posts