Condo Insurance in Texas: What Your HOA Policy Doesn't Cover
What condo insurance in Texas actually covers (and what it doesn't)
If you own a condo in Texas, you've probably heard that your HOA has insurance and assumed you were mostly covered. That assumption costs condo owners thousands of dollars every year. Condo insurance in Texas is different from a standard homeowners policy, and understanding the gap between your HOA's master policy and your own coverage is the most important step you can take to protect your investment.
Here is exactly where your HOA's coverage stops and where your personal condo policy needs to pick up.
How HOA master policies work in Texas
Your condo association carries a master insurance policy that covers the building's common areas, the exterior structure, and shared systems like the roof, hallways, and elevators. That policy protects the association's interests, not yours. When a pipe bursts or a fire damages your unit, the master policy may pay for the building shell and little else.
Texas HOA master policies typically fall into one of two categories:
- Bare walls-in : covers only the building structure up to the bare drywall. Fixtures, flooring, cabinets, and anything you installed or upgraded are your responsibility.
- All-in (or all-inclusive) : covers original fixtures and built-in appliances, but still excludes your personal belongings, improvements you made above the original spec, and your personal liability.
Most owners have no idea which type their HOA carries. Pull your condo association's declarations page and read it. If you can't get a copy, ask your property manager directly. What you find will shape how much coverage you need on your own condo policy.
What your personal condo policy covers
A standard HO-6 policy, the form used for condo owners in Texas, is built to fill the gaps your HOA leaves behind. It typically covers:
- Dwelling coverage (Coverage A) : pays to repair or rebuild the interior of your unit, including walls, flooring, cabinets, built-in appliances, and any improvements you've made. If your HOA has a bare walls-in master policy, this coverage matters most.
- Personal property (Coverage C) : replaces your furniture, electronics, clothing, and other belongings if they're stolen, damaged by fire, or destroyed by a covered event. Texas hailstorms, kitchen fires, and burst pipes are real risks here.
- Liability protection (Coverage E) : pays legal and medical costs if someone is injured inside your unit or if you accidentally damage a neighbor's property. A leaky dishwasher that damages the unit below you is a liability scenario your HOA policy will not touch.
- Loss of use (Coverage D) : covers hotel stays and temporary living expenses if your unit becomes uninhabitable after a covered loss.
- Loss assessment coverage : if your HOA suffers a major loss that exceeds its own policy limits, the association can levy a special assessment against all unit owners. Loss assessment coverage pays your share, up to your policy limit. This surprises a lot of owners.
The gaps that catch Texas condo owners off guard
Even with a solid HO-6 policy in place, there are situations where you can end up underinsured. These are the most common gaps we see for condo owners across the Dallas-Fort Worth area:
Flood damage
Neither your HOA's master policy nor a standard HO-6 policy covers flood damage. If your building sits in or near a flood zone, or if a neighbor's burst pipe causes flooding in your unit, you may need a separate flood policy. The personal flood insurance options available through private carriers and the National Flood Insurance Program (NFIP) are worth reviewing before you need them, not after.
High-value personal property
Standard HO-6 policies set sub-limits on jewelry, fine art, collectibles, and electronics. A $5,000 diamond ring may only be covered up to $1,500 under a base policy. If you own items like that, a scheduled endorsement or a separate jewelry insurance policy closes that gap quickly.
Actual cash value vs. replacement cost
Some HO-6 policies pay actual cash value for personal property, meaning they subtract depreciation before writing a check. A five-year-old laptop that cost $1,200 might only pay out $400. Replacement cost coverage pays what it actually costs to buy a comparable new item. The small premium difference is usually worth it.
Unit improvements and upgrades
If you upgraded your kitchen countertops from laminate to quartz or added hardwood floors, those improvements are almost certainly not covered under a bare walls-in HOA policy. Your HO-6 dwelling coverage needs to reflect those upgrades. If you haven't updated your coverage limits since you bought the unit, there's a good chance you're underinsured.
Loss assessment shortfalls
Texas HOAs have been hit with major storm damage in recent years, and special assessments can run into the tens of thousands of dollars per unit after a catastrophic hail event or fire. Standard loss assessment coverage often starts at $1,000 to $5,000, which may not be enough. Ask about higher limits when you shop.
How much does condo insurance cost in Texas?
Texas is one of the more expensive states for property insurance, and condo coverage reflects that. A typical HO-6 policy in the DFW metro area runs $500 to $1,200 per year , depending on the location of your condo, the age of the building, your coverage limits, and the deductible you choose.
A few factors that drive costs up in North Texas specifically:
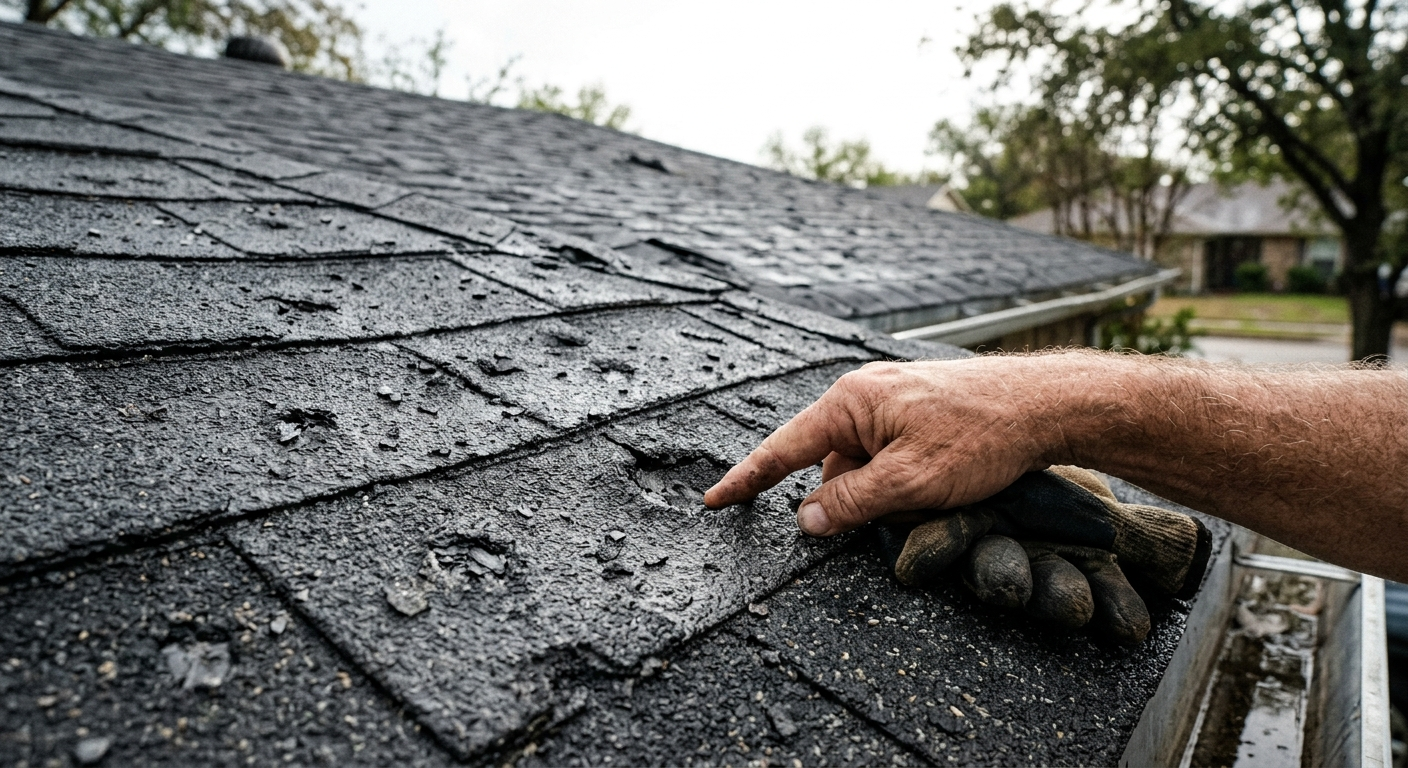
- Hail exposure : the DFW area is part of Hail Alley. Carriers price this risk into every property policy. Condo buildings with older roofs often carry surcharges.
- Wind deductibles : many Texas policies have separate wind and hail deductibles, often calculated as a percentage (1% to 2%) of your insured value rather than a flat dollar amount. Know yours before storm season.
- Building age and construction type : older wood-frame buildings carry higher rates than newer concrete construction.
- Your loss history : prior claims on your record or your HOA's building can push rates higher.
Because Texas rates vary significantly by carrier, working with an independent agent who can run quotes across multiple companies is the most effective way to find solid coverage at a competitive price. The difference between the highest and lowest quote for the same coverage can easily be $300 to $500 per year .
What to look for when comparing condo policies in Texas
Not all HO-6 policies are built the same. When you're reviewing options, focus on these details:
- Coverage basis (replacement cost vs. ACV) : always push for replacement cost on personal property and dwelling coverage.
- Loss assessment limit : request at least $10,000 to $25,000 if your HOA's master policy limits are anywhere close to the building's full replacement value.
- Water backup and sewer coverage : not automatically included, but important in older condo buildings. Ask about adding it as an endorsement.
- Deductible structure : understand whether your wind/hail deductible is a flat dollar amount or a percentage. A 2% deductible on a $200,000 condo interior means you pay the first $4,000 out of pocket before insurance applies.
- Policy exclusions : read what's excluded. Earth movement, intentional acts, and certain mold situations commonly appear in exclusion lists.
It also helps to compare your HO-6 dwelling limit against what your HOA's master policy actually covers. If your HOA has a bare walls-in master policy and your unit interior would cost $80,000 to rebuild, your Coverage A limit should reflect that number, not a round figure you guessed when you filled out the application.
Condo insurance and your Texas HOA: understanding the coordination
One scenario that creates confusion every year: damage that starts in a shared area but enters your unit. Say a pipe in the wall (shared infrastructure) bursts and ruins your flooring and cabinets. The HOA's master policy may cover the pipe repair. Whether it covers your interior damage depends on the type of master policy. If it doesn't, your HO-6 steps in.
This is why the coordination between your policy and the HOA's policy matters. Your agent should review the HOA's declarations page as part of the quoting process so the two policies align. Gaps cost you money. Overlapping coverage isn't necessarily bad, but it can mean you're paying premiums twice for the same protection.
Texas condo owners in communities where the HOA is active and well-funded tend to have fewer assessment surprises. But even well-run HOAs have been caught short after major hail seasons. The 2016 and 2019 hailstorms across the DFW metroplex left dozens of associations facing insurance shortfalls and triggering assessments against unit owners. If you were in one of those buildings without loss assessment coverage, the bill was yours to absorb.
It's also worth knowing that Texas law (under the Texas Property Code, Chapter 82 for condominiums) gives HOAs specific authority over how insurance is carried for the common elements. As a unit owner, you are responsible for everything from the interior surfaces inward unless your HOA's master policy explicitly states otherwise. Don't assume.
Get the right condo insurance in Texas with Firstline Insurance Agency
Firstline Insurance Agency is an independent agency serving condo owners across North Texas, including Fort Worth, Arlington, Keller, Southlake, Colleyville, Mansfield, and the surrounding communities. As an independent agency, we shop your coverage across multiple carriers to find the right fit at a competitive rate, rather than pushing a single company's product.
We'll review your HOA's master policy alongside your personal HO-6 options to make sure the two work together and that you're not left holding the bill for something you thought was covered. Whether you're buying your first condo, refinancing, or questioning whether your current policy is doing its job, we're glad to take a look.
Call us at (817) 618-5480 or reach out through our contact page to get started. A quick conversation now is a lot easier than filing a claim and discovering a gap you didn't know was there.
Get A Quote
At Firstline Insurance Agency, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Firstline Insurance Agency
Recent Posts