Mobile Home Insurance in Texas: Coverage, Cost & What to Know
What mobile home insurance in Texas actually covers
Mobile home insurance in Texas works differently than a standard homeowners policy, and many owners don't discover that until they file a claim. If you own a manufactured or mobile home, you need a policy written specifically for that type of structure. A traditional HO-3 policy won't cover it, and leaving that gap open in a state with hailstorms, tornadoes, and flash flooding is a real risk.
The structure itself
The "dwelling" portion of a mobile home policy covers the physical structure against named perils: wind, hail, fire, lightning, and vandalism, among others. Some carriers write these policies on an open-peril basis, meaning everything is covered unless specifically excluded, but many manufactured home policies are named-peril only. Read the declarations page carefully. In Texas, where hail damage is one of the most common causes of claims, confirming that wind and hail are covered is non-negotiable.
Personal property
Your furniture, appliances, clothing, and electronics are covered under the personal property section, typically up to a set limit. Most base policies set this between $20,000 and $60,000 , but you can increase it. High-value items like jewelry or collectibles may need a separate scheduled endorsement to be fully protected. If you want to understand how jewelry coverage works alongside a broader home policy, our guide on jewelry insurance in Texas walks through the details.
Liability coverage
Liability pays if someone is injured on your property or you accidentally damage someone else's property. Standard limits are usually $100,000 , though an umbrella policy can extend that significantly. This portion works similarly to a standard homeowners policy.
Additional living expenses
If a covered loss makes your home unlivable, additional living expense (ALE) coverage helps pay for a hotel, short-term rental, or meals while repairs happen. The limit varies by carrier, so compare carefully.
How manufactured home insurance differs from standard homeowners
Texas has more manufactured housing units than almost any other state, and the insurance market reflects that. Even so, there are real differences buyers need to understand before signing anything.
HUD code vs. site-built construction. Manufactured homes built after June 15, 1976 must meet HUD standards. Homes built before that date are often called "mobile homes" and can be much harder to insure. Carriers may require an inspection or refuse coverage entirely for pre-HUD units. If your home was built before 1976, call an independent agent before assuming you can get coverage through a standard online platform.
Replacement cost vs. actual cash value. This is where many policyholders get hurt. Manufactured homes depreciate differently than site-built homes. An actual cash value (ACV) policy pays what the home is worth at the time of the loss, not what it costs to replace it. After depreciation, that number can be far lower than expected. Replacement cost coverage costs more per year but protects you from that shortfall. In Texas, where severe weather can total a home quickly, the difference matters.
On a permanent foundation vs. in a park. Where your home sits affects your coverage options. A manufactured home on a permanent foundation with land may qualify for some modified homeowners policies. A home in a mobile home park, or one that has never been placed on a permanent foundation, will almost certainly need a specialized manufactured home policy. Some parks also require coverage minimums, so check your lease.
Texas risks that make adequate coverage essential
North Texas and the surrounding region see some of the most concentrated severe weather in the country. That reality shapes what "adequate coverage" means for manufactured homeowners here.
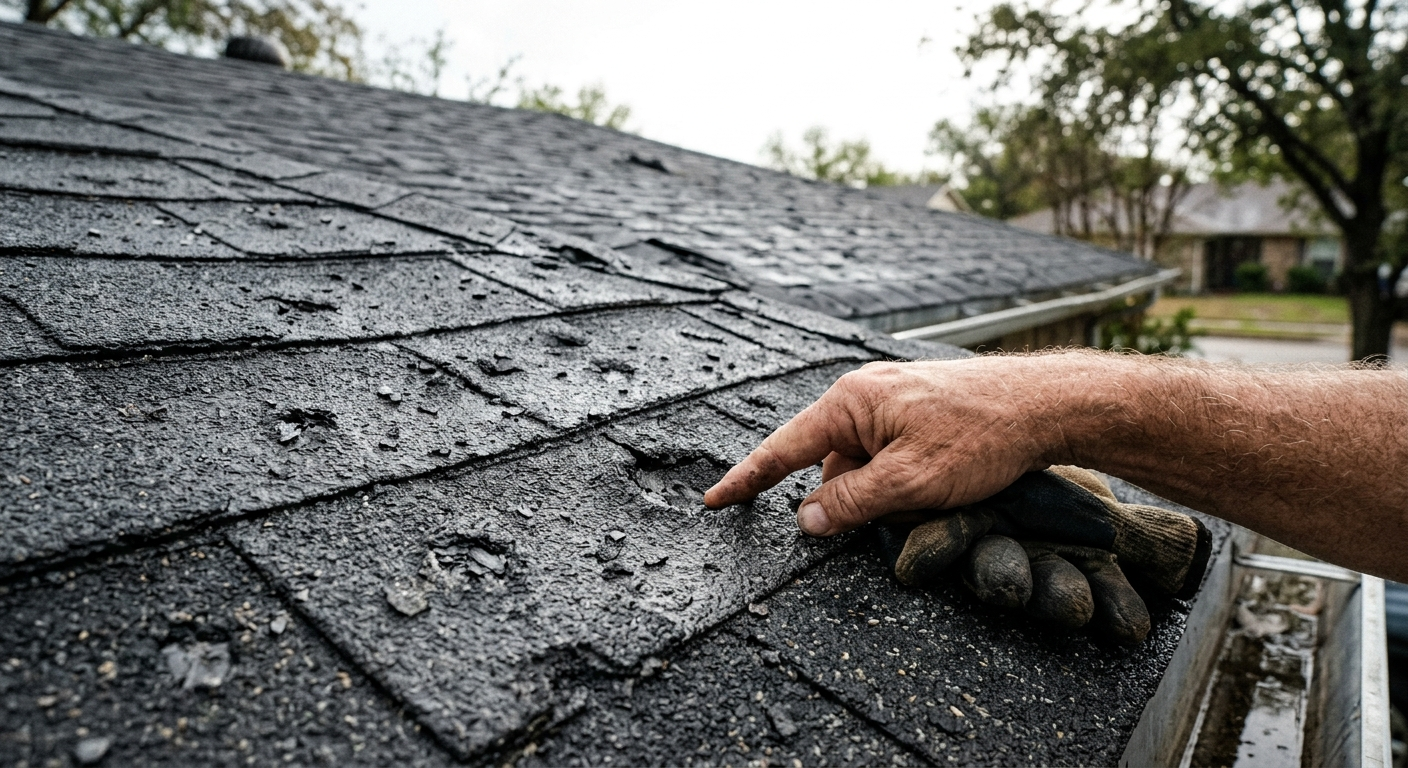
- Hail. Tarrant, Parker, and Hood counties all sit in the hail belt. Golf ball and baseball-sized hail is not unusual, and a single storm can destroy a mobile home roof. If you've already filed a hail claim or need to, our breakdown of hail damage home insurance claims in Texas covers the process step by step.
- Tornadoes. Manufactured homes offer less wind resistance than site-built structures. Tornado warnings in North Texas are common in spring and early summer, and evacuation plans matter as much as the insurance policy itself.
- Flooding. Standard mobile home policies, like all standard homeowners policies, exclude flood. If your home is in or near a floodplain or low-lying area, a separate flood policy through the National Flood Insurance Program (NFIP) or a private carrier is worth serious consideration. Learn more about your options with our guide on personal flood insurance in Texas.
- Theft and vandalism. Manufactured homes in rural areas or in parks with limited security can be more vulnerable to break-ins. Confirm your policy covers theft of personal property and any detached structures like a shed or carport.
What mobile home insurance costs in Texas
Most Texas manufactured homeowners pay somewhere between $700 and $1,800 per year for a standard policy, though that range shifts based on several variables. There is no single average that applies broadly, because the market for manufactured home insurance is more fragmented than the market for traditional homeowners coverage.
Factors that raise or lower your premium
- Age and condition of the home. Older homes cost more to insure and may be limited to ACV coverage only. Newer HUD-compliant homes built in the last 10 to 15 years generally get better rates.
- Location. A home in a high-wind or flood zone costs more to insure. ZIP codes in and around Fort Worth, Granbury, or Weatherford all carry different risk profiles.
- Coverage limits and deductibles. Higher deductibles lower your premium but mean more out-of-pocket after a loss. Many Texas manufactured home policies now carry a separate wind and hail deductible, often expressed as a percentage (1% to 5%) of the insured value rather than a flat dollar amount.
- Claims history. Past claims, especially weather-related ones, can significantly affect what carriers will offer and at what price.
- Security and safety features. Tie-down anchoring systems, smoke detectors, and security systems may earn discounts depending on the carrier.
Why comparing carriers matters more here
The manufactured home insurance market in Texas has fewer carriers than the broader homeowners market. Rates vary much more from one insurer to another, which makes shopping across multiple companies worthwhile. An independent agent with access to several carriers is in a much stronger position to find a competitive rate than a single-company agent who can only offer one option.
Common coverage gaps to watch for
A policy that looks solid on the surface can still leave you exposed if you haven't read past the declarations page. These are the gaps that come up most often with manufactured home coverage in Texas.
Trip coverage. If you ever need to move your mobile home to a new location, standard policies typically do not cover damage that occurs during transport. You need a separate trip permit and transit coverage arranged before the move. Without it, any damage during the haul is your expense.
Detached structures. A carport, storage shed, or detached garage near your home may not be automatically covered under the base policy. Ask your agent specifically about "other structures" coverage and its limits.
Skirting, steps, and decks. These are often excluded or subject to lower sub-limits. Replacing skirting after a windstorm seems minor, but costs add up quickly once materials and labor are included.
Ordinance or law coverage. If a partial loss triggers a local requirement to bring the entire home up to current building codes, which can happen with older manufactured units, ordinance or law coverage pays for that difference. Without it, that extra cost falls on you.
Vacancy issues. If you leave the home vacant for 30 to 60 days (limits vary by carrier), some policies suspend certain coverages or allow the carrier to cancel. If you have a second home, a seasonal property, or are between tenants on a rental unit, confirm your policy terms. For longer-term vacant situations, see our guide to vacant property insurance in Texas.
Tips for buying mobile home insurance in Texas
Whether you're buying a new manufactured home or reviewing coverage you've had for years, these steps can help you avoid common mistakes.
- Get the replacement cost figure, not just market value. Ask your carrier or agent what it would actually cost to replace the structure with a comparable new unit. That number should drive your dwelling limit, not the purchase price or tax appraisal.
- Review the wind and hail deductible. Confirm whether it's a flat deductible or a percentage. If it's a percentage, calculate what that means in real dollars on your insured value. A 2% deductible on a $150,000 home is $3,000 out of pocket before the carrier pays anything on a wind or hail claim.
- Check for excluded perils. Named-peril policies list what's covered. Open-peril policies list what's excluded. Know which type you have and read the exclusion list.
- Ask about liability. If you frequently have guests, rent out space, or have a trampoline or pool, confirm your liability limit is adequate. A base limit of $100,000 can disappear fast in a serious injury claim.
- Consider a flood policy separately. No manufactured home policy includes flood coverage. The NFIP offers coverage for structures under certain conditions, and private flood carriers may offer broader terms. Get a quote on both.
Get the right manufactured home coverage with Firstline Insurance Agency
Firstline Insurance Agency is an independent agency serving manufactured homeowners across the Fort Worth area, including Arlington, Granbury, Weatherford, Burleson, and the surrounding communities. As an independent agency, we work with multiple insurance carriers, which means we can compare options across the market and find coverage that fits your home, your location, and your budget. You don't have to take whatever one company offers.
Mobile home insurance in Texas is one of those coverage areas where the details really matter. The difference between an ACV policy and a replacement cost policy, or between a named-peril and an open-peril form, can mean tens of thousands of dollars if you ever file a claim after a hailstorm or tornado. Getting that right at the start is far less painful than sorting it out after the loss.
Ready to compare rates and get the right coverage? You can reach Firstline Insurance Agency at (817) 618-5480 or request a quote online. You can also learn more about all of our personal coverage options on our manufactured home insurance page. We're here to help you make a smart, informed decision, not just hand you a policy and move on.
Get A Quote
At Firstline Insurance Agency, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Firstline Insurance Agency
Recent Posts